
Understanding captive insurance
Captive insurance provides businesses with an alternative way to manage and finance their own risks rather than relying entirely on the traditional insurance market.
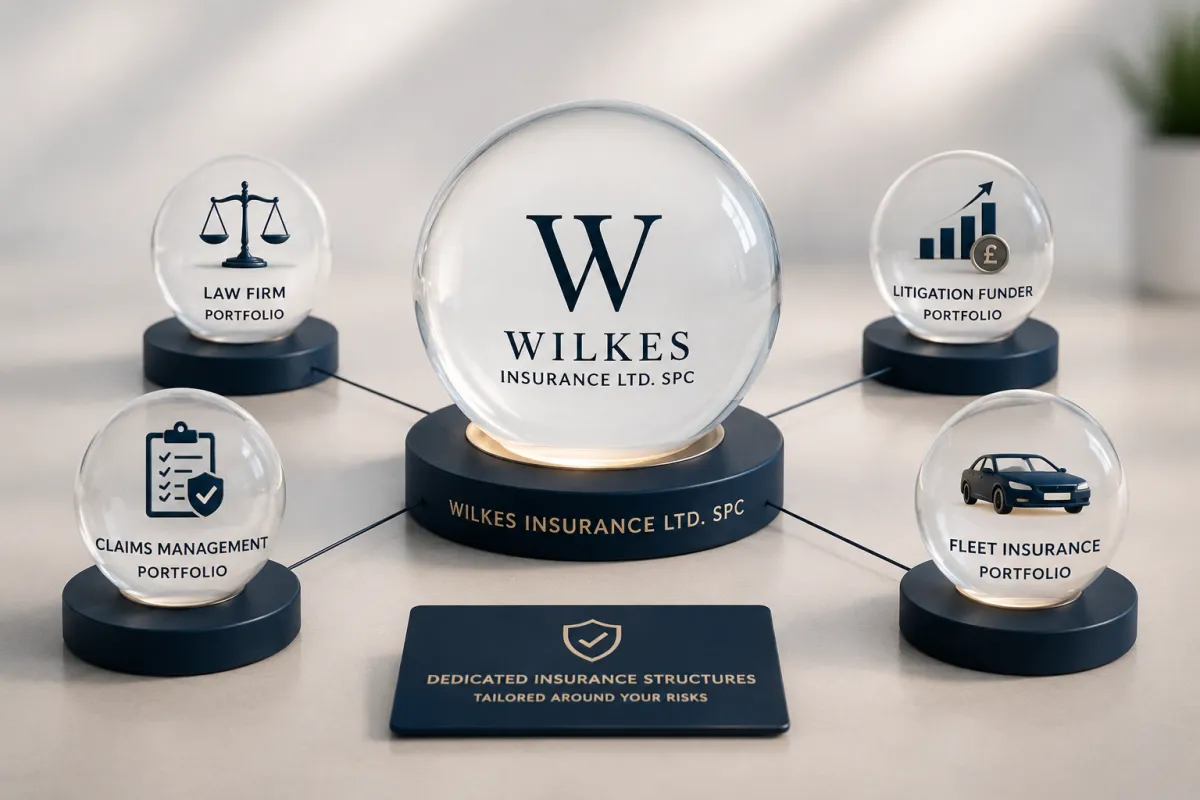
Through a segregated portfolio within Wilkes Insurance Ltd. SPC, an organisation can establish a dedicated insurance programme designed around its own risks, claims experience and commercial requirements — without needing to establish a standalone insurance company.
This can provide greater control over underwriting, coverage and risk management, while allowing the programme to develop as the organisation's experience and insurance requirements evolve.
Take Greater Control of Your Insurance
Traditional insurance is designed for a broad market. A captive programme can be designed around your business.
Whether you are a law firm managing litigation risk, a litigation funder supporting portfolios of claims, a claims management company handling high volumes of cases, or a business operating a substantial vehicle fleet, your risks have their own characteristics.
A segregated portfolio within Wilkes Insurance Ltd. SPC can provide a dedicated insurance structure in which premiums, underwriting criteria, policy limits and risk management arrangements are developed around the needs and risk profile of your business.
Instead of simply purchasing an off-the-shelf insurance product, you can participate in building an insurance programme specifically designed around the risks you understand.
Benefits of Captive Insurance
With conventional insurance, premiums are generally paid to an insurer regardless of how your individual portfolio ultimately performs.
A captive structure changes that relationship.
By retaining an appropriate proportion of risk within a dedicated insurance programme, favourable underwriting performance can potentially benefit the captive rather than being entirely transferred to the conventional insurance market.
For organisations with sufficient scale, strong case selection, effective claims management or a well-managed loss history, this creates an opportunity to participate more directly in the financial performance of the risks they generate.
The result is a closer alignment between good risk management and the long-term performance of your insurance programme.
More Benefits of Captive Insurance
Cost Savings - Reduce premium expenses and retain underwriting profits
Tailored Coverage - Design policies that precisely match your risk profile
Enhanced Claims Control - Manage claims processes directly and efficiently
Risk Management Excellence - Gain deeper insights into your risk exposures
Profit Retention - Keep underwriting profits within your organisation
Tax Efficiency - Explore potential tax advantages (consult with tax advisors)
Increased Control - Direct oversight of your entire insurance program
Coverage for Unique Risks - Insure risks that traditional markets won't cover

Build an Insurance Programme That Grows With You
Your insurance requirements today may be very different from those of your business in three or five years.
A captive programme can evolve alongside your organisation.
As volumes increase and actual claims experience develops, underwriting criteria, premiums, policy limits, capital requirements and risk retention can be reviewed against the performance of the portfolio.
Where appropriate, additional protection may also be incorporated through access to highly rated reinsurance capacity, allowing suitable risks to be retained within the captive while additional layers of risk can be transferred.
This creates an insurance structure capable of developing with your business rather than requiring your business to continually adapt to a standard insurance product.
Could a Captive Work for Your Business?
Every successful captive starts with understanding the risk.
Whether you are a law firm, litigation funder, claims management company or business looking for greater control over your insurance programme, Wilkes can help you explore whether a segregated portfolio is appropriate for your organisation.
We begin by understanding your existing insurance arrangements, risk profile, claims experience, volumes and commercial objectives before considering how a captive programme could be structured around your business.
Start the conversation with Wilkes Insurance Ltd. SPC and explore what your own insurance programme could look like.

Get In Touch
